Bank of Baroda has operated in the UAE since 1974, and it holds something no other Indian bank in the country does: a full UAE banking licence. That single fact shapes how it works here. Instead of chasing Emirates NBD or Mashreq on premium apps and rewards, it runs a focused operation built around three things Indian residents actually use it for: salary accounts under the Wages Protection System, NRE and NRO accounts, and moving money home to India.
The bank is regulated by the Central Bank of the UAE and runs as a mainland branch network. Its parent, Bank of Baroda, is a government-owned Indian bank founded in 1908. That parent carries a Fitch rating of BBB-, affirmed in February 2026, which puts the institution behind your deposits on stable, investment-grade footing.
Bank of Baroda UAE: the essentials
| Detail | Information |
|---|---|
| In the UAE since | 1974 |
| Licence | Only Indian bank with a full UAE banking licence |
| Regulator | Central Bank of the UAE |
| Branch network | 5 full branches across 4 emirates |
| Service units | 9 Electronic Banking Service Units (EBSUs) |
| ATMs | 45+ |
| Parent | Bank of Baroda (India), government-owned, founded 1908 |
| Credit rating | Fitch BBB- (parent, affirmed February 2026) |
| Built for | India remittance, WPS salary accounts, NRE/NRO banking |
| Less suited to | Premium digital banking, UAE credit cards |
Where Bank of Baroda operates in the UAE
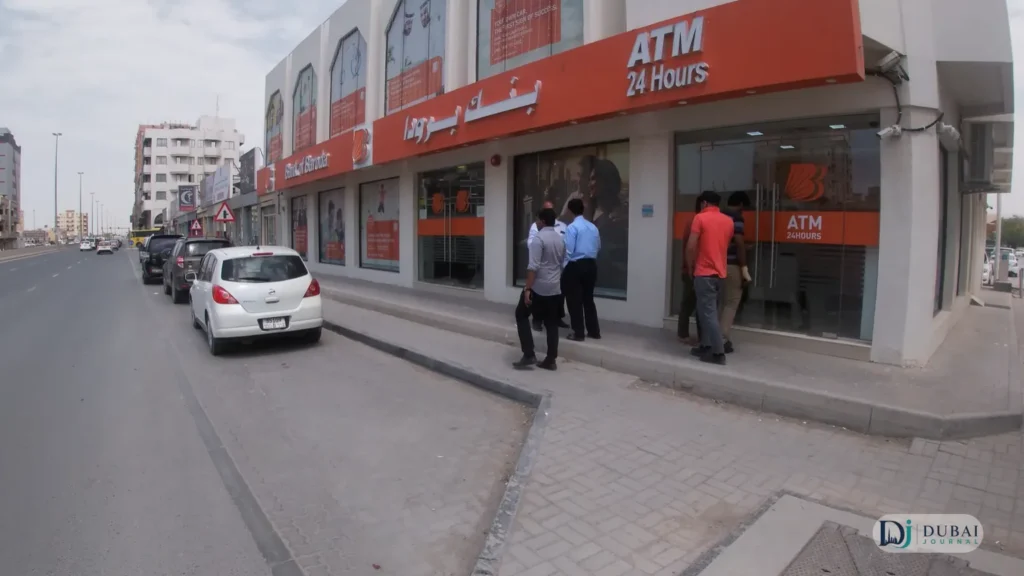
Bank of Baroda runs 5 full branches, 9 EBSUs, and more than 45 ATMs across four emirates. You can run a balance inquiry at those machines the same way as any UAE ATM. The five branches sit in Dubai, Deira, Sharjah, Abu Dhabi, and Ras Al Khaimah.
| Emirate | Branch location |
|---|---|
| Dubai | Karama (also the zonal head office) |
| Dubai | Deira |
| Sharjah | Buhaira Corniche |
| Abu Dhabi | Hamdan Bin Mohammed Street |
| Ras Al Khaimah | Al Nakheel |
Dubai and Deira are both in Dubai emirate, which is why the count comes to five branches but four emirates.
One point worth clearing up: several directories list “9 customer service centers” next to the branches as though they were a separate tier. They are the same 9 EBSUs under a different label. And any listing showing six branches, or an Al Ain branch, is out of date. The Al Ain branch has closed, and those accounts moved to Abu Dhabi.
What an EBSU actually is
An Electronic Banking Service Unit is a staffed self-service point, smaller than a full branch. Use one for routine deposits, cash transactions, account queries, and remittance kiosks. Go to a full branch when you need account opening, a loan, document verification, or a relationship manager.
The accounts, and who each one is for
Bank of Baroda UAE’s retail range is built around savings, salary, and deposit accounts. There is no UAE-issued consumer credit card here. Card issuance is limited to debit cards linked to your account, so if a credit card is what you’re after, this is not the bank for it.
| Account | Who it’s for |
|---|---|
| Savings Account | GCC or Indian nationals and PIOs wanting a standard interest-bearing account |
| Zero Balance WPS Account | Workers paid through the Wages Protection System |
| Non-Resident Savings (NRE/NRO) | NRIs managing UAE property, investments, or income from abroad |
| Baroda Happiness Twin Account | NRIs wanting a combined current-and-savings setup |
| Premium Salary Account | Salaried residents wanting a fuller-featured salary account |
Eligibility narrows more than most guides mention. The standard savings, current, and non-resident accounts are open to GCC nationals and Indian nationals including Persons of Indian Origin, per the bank’s savings account terms. The exception is the Zero Balance WPS account, which any UAE worker paid through WPS can open regardless of nationality. Accounts can also be opened in a minor’s name and operated by a parent until the child turns 21.
On balances and returns, the standard savings account pays 0.40% a year and asks for an AED 1,000 minimum balance to avoid charges. The WPS account pays the same 0.40% with no minimum at all, which is the main reason blue-collar workers pick it. Non-resident savings accounts can be held in AED, USD, GBP, or EUR.
Opening an account, and why you can’t finish online
You cannot open a Bank of Baroda UAE account entirely online. The website form only registers your interest. Completing the account means visiting a branch in person to sign the forms in front of a bank officer and hand over original documents. If you come across a fully digital video-KYC flow while searching, that is the process for resident Indians opening an account in India, not the UAE account.
The actual sequence:
- Collect the account opening form from a branch, or start the interest form on the website.
- Gather your documents.
- Visit a branch to submit originals and sign in front of a bank officer.
- Collect your debit card and register for internet and mobile banking during the same visit.
Documents to bring:
- Passport with a valid UAE residence visa page
- Emirates ID
- Salary certificate or labour contract, for a salary account
- Tenancy contract or Ejari, where applicable
- Sponsor NOC if the sponsor’s name differs on your visa
- Passport-size photographs
Sending money to India
The bank’s in-house channel is Rapid Funds2India, available through ATMs, internet banking, the mobile app, and branches or EBSUs. If you’re receiving an international wire into another UAE bank instead, you’ll need that bank’s SWIFT code, such as the DIB SWIFT code. Transfers are free when both the sender and the beneficiary hold Bank of Baroda accounts. Otherwise standard charges apply.
What you need to send depends on the amount, and the tiers are set by the bank’s documentation rules rather than by any flat fee bracket:
- Any remittance: a completed request form from the branch.
- Above AED 2,000: add a copy of your labour card.
- Above AED 40,000: add your passport, work permit, and proof of the source of funds.
The dirham-to-rupee rate is set daily on market conditions and is only fixed at the moment the transfer is made. One thing that trips up searchers: Baroda RemitXpress, which sometimes shows up alongside Rapid Funds2India, is the bank’s remittance product for customers in the US, UK, and Eurozone, not the UAE.
Digital banking, and what users actually say
Two channels handle everything digital: Baroda Connect for internet banking, and the bob World UAE app, renamed from M-Connect Plus UAE, for mobile.
Registration is not self-service. You submit a form at your base branch, which then enables the facility and issues your four-digit mPIN. The app itself draws steady criticism in its app store reviews, where users report registration failures and reliability problems, and its rating sits well below what UAE customers expect from a banking app. If a polished mobile experience is central to how you bank, this is the bank’s weakest area.
Who it suits, and who should look elsewhere
It’s a strong fit if you’re:
- An Indian resident who sends money home regularly and wants free Bank of Baroda-to-Bank of Baroda transfers
- A worker paid through WPS who needs a genuine zero-balance account
- An NRI managing NRE or NRO accounts and UAE property or investments from abroad
- Someone who values a 50-year-old, fully licensed, well-rated institution over app polish
Look elsewhere if you:
- Want a UAE credit card or a rewards programme
- Rely on a fast, dependable mobile app day to day
- Need to open and run everything remotely without setting foot in a branch
FAQ
Is Bank of Baroda in the UAE?
Yes. It has operated in the UAE since 1974 and is the only Indian bank with a full UAE banking licence, running five branches and nine EBSUs across four emirates.
Can I open a Bank of Baroda UAE account online?
No. The online form only starts the process. You must visit a branch in person with original documents to complete KYC and sign the account forms.
Can I open an NRE or NRO account from the UAE?
Yes. Non-resident savings accounts are available to Indian nationals and PIOs with a financial interest in the UAE, and can be held in AED, USD, GBP, or EUR. Internet banking for non-residents is view-only.
Does Bank of Baroda UAE offer credit cards?
No. Its UAE card issuance is limited to debit cards linked to your account. There is no UAE-issued consumer credit card in the personal banking range.
How many branches does Bank of Baroda have in the UAE?
Five full branches, in Dubai (Karama), Deira, Sharjah, Abu Dhabi, and Ras Al Khaimah, plus nine EBSUs. Older listings showing six branches or an Al Ain branch are out of date.
Is my money safe with Bank of Baroda UAE?
It operates under a full Central Bank of the UAE licence, and its parent carries a Fitch rating of BBB- affirmed in February 2026, which indicates a stable, investment-grade institution.
Before you go in
- Check the current fees and minimum balance for your account type on the bank’s service charges schedule.
- Bring originals, not just copies, for KYC verification.
- Use the branch and ATM locator to find your nearest branch or EBSU before you travel.
- If you send money to India often, ask about setting up Rapid Funds2India when you open the account.
